
Learning how to budget on a low income is not about willpower or cutting out every small pleasure in your life. It is about building a system that works when there is not much margin for error. Most budgeting advice assumes a comfortable salary and plenty of room to maneuver. This guide is written for everyone else: people covering rent, food, and bills on $1,400 to $1,800 a month and wondering where the money disappears to. You will get a realistic framework, worked examples with real numbers, strategies for debt, and pointers to free assistance programs you may already qualify for.
How to Budget on a Low Income When Standard Advice Fails
The classic 50/30/20 rule says to spend 50% on needs, 30% on wants, and 20% on savings. It is tidy, memorable, and completely unrealistic for many households. When rent alone eats 45% of your take-home pay, there is no universe in which 30% goes to “wants.” Advice built for median incomes quietly assumes housing costs behave — and for low-income households, they often do not.
That does not mean budgeting is pointless when money is tight. It means the opposite: when every dollar has a job, a budget matters more, not less. The fix is not to try harder at a framework designed for someone else. The fix is a framework designed for your numbers. That is what the rest of this guide builds, step by step.
Step 1: Find Your Real Number
Your budget starts with one figure: your actual take-home pay — the money that lands in your account after taxes and deductions. Not your hourly rate times forty, not your salary on paper. If your income varies month to month, use the lowest amount you earned in any of the last three months as your planning number. Planning from your worst month means the budget still holds when work slows down; anything extra in a good month becomes a bonus you can direct deliberately.
List every income source: your main job, part-time shifts, gig work, child support, disability payments, and any benefits you receive. People routinely forget the small, irregular ones — a $40 cash job here, a $25 rebate there — and then wonder why the math never quite closes. Write it all down. This number is the foundation of everything that follows.
Step 2: Track Where the Money Actually Goes
Before you change a single habit, spend two to four weeks recording every dollar you spend. Not from memory — from bank statements, receipts, and a notes app on your phone. Most people who do this exercise find at least one surprise: subscriptions they forgot, fees they never noticed, or a pattern of small purchases that adds up to real money.
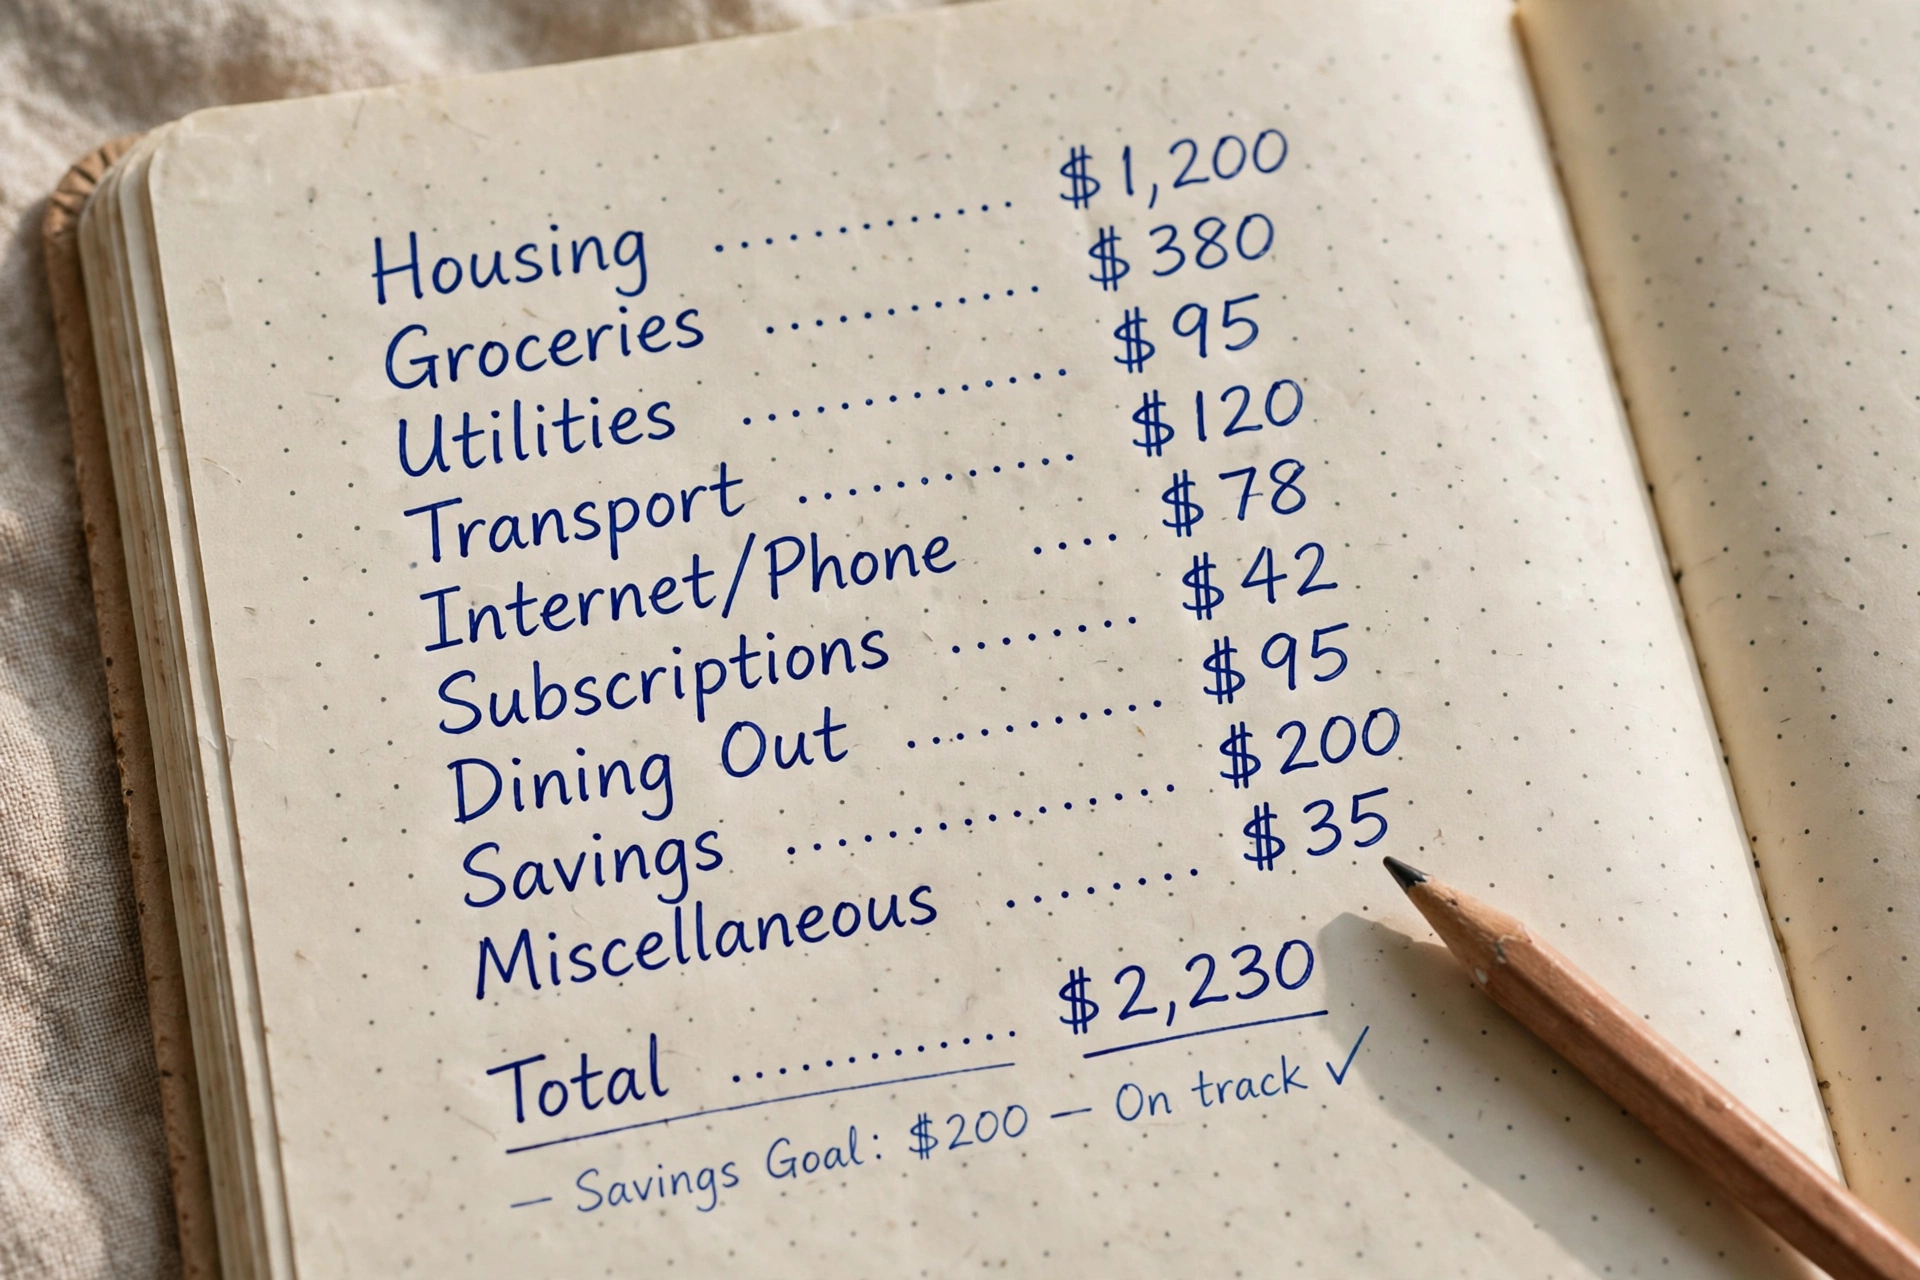
Sort everything into two buckets: fixed (rent, insurance, loan payments, phone plan) and variable (groceries, gas, household supplies, everything else). Do not judge the numbers yet. This step is reconnaissance, not a diet. You cannot fix a leak you have not found, and you cannot set realistic spending targets without knowing what “realistic” looks like for your life. Free budgeting worksheets and tools from the Consumer Financial Protection Bureau can make this tracking step easier if you want a structured template rather than a blank page.
Step 3: Use a Split Built for Tight Incomes
Here is the framework: the adapted 70/20/10 split. If you are learning how to budget on a low income, this split is a realistic place to start. On a low income, your needs will often take around 70% of take-home pay, not 50%. Fighting that reality breeds guilt and abandoned budgets. Instead, plan for it:
- 70% — Needs: housing, food, utilities, transportation, insurance, minimum debt payments.
- 20% — Savings and extra debt payments: an emergency buffer first, then attacking high-interest balances.
- 10% — Flex: a small, guilt-free amount for the things that keep life livable. This is not a luxury — it is what keeps the budget sustainable.
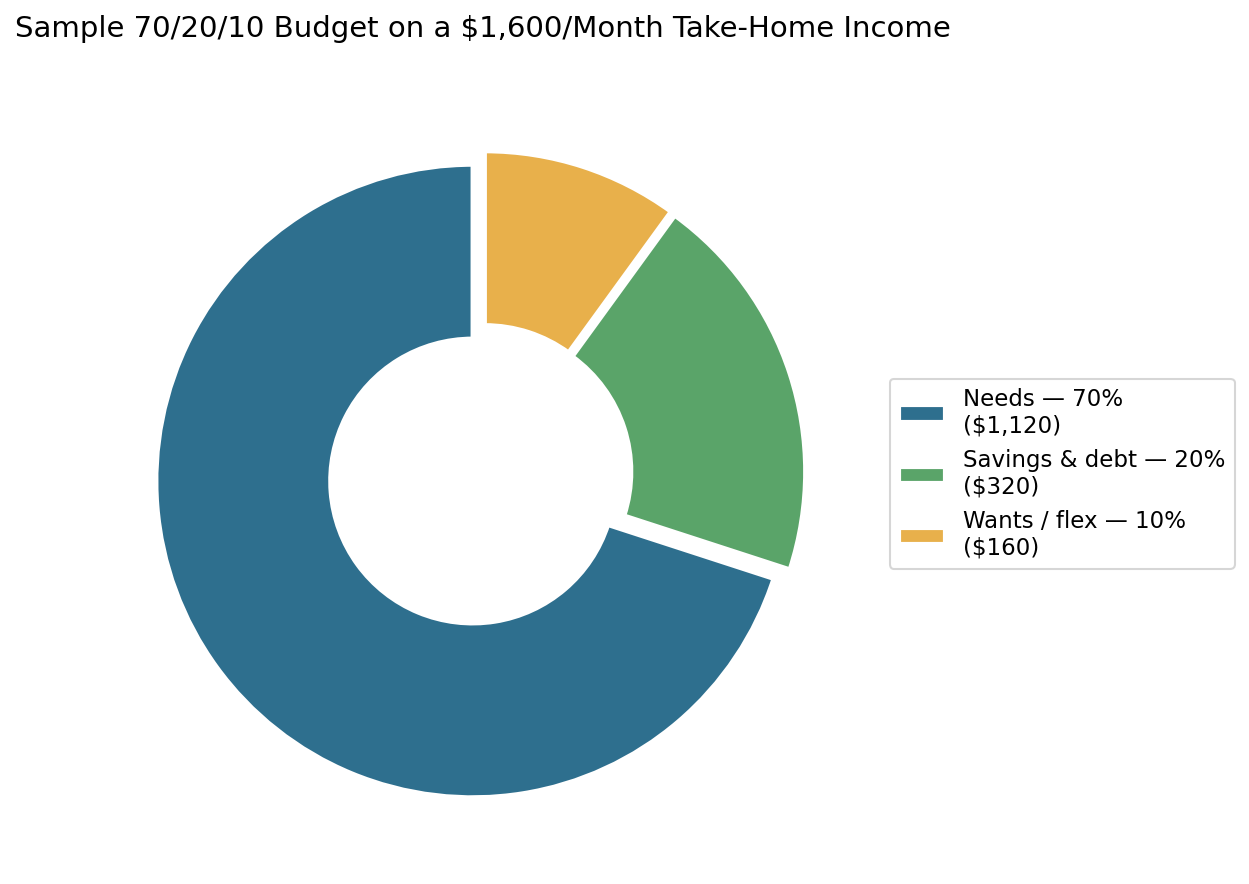
The chart above shows how this looks on a sample $1,600/month take-home income: $1,120 for needs, $320 for savings and debt, and $160 of breathing room. These are illustrative figures for a sample household — your own split should come from your real numbers in Steps 1 and 2. The point of the framework is the order of operations: needs covered first, future-you funded second, and a deliberate small slice for now.
70/20/10 vs. the Alternatives on a Low Income
| Framework | Needs | Savings/Debt | Wants/Flex | Verdict for low income |
|---|---|---|---|---|
| 50/30/20 (classic) | 50% | 20% | 30% | Needs cap is unrealistically low; sets you up to “fail” |
| 70/20/10 (adapted) | 70% | 20% | 10% | Honest about housing costs; keeps savings habit alive |
| 60/30/10 (debt-focused) | 60% | 30% | 10% | Good temporary mode when attacking high-interest debt |
| Zero-based (every dollar assigned) | varies | varies | varies | Powerful but time-intensive; great once the habit sticks |
If your needs genuinely exceed 70%, do not panic and do not quit. That is information, not failure — it tells you the budget alone cannot close the gap and the income side needs attention (more on that in Step 7). And if you cannot manage 20% to savings yet, start with 5% or even 2%. A $30 monthly transfer you actually keep is worth more than a $300 target you abandon by week two.
Worked Examples: $1,400, $1,600, and $1,800 a Month
Abstract percentages become concrete fast with real numbers. Below are three sample monthly budgets using the 70/20/10 framework. These are illustrative examples for typical single-household spending patterns — adjust every line to your own costs.
Sample budget on $1,400/month take-home
- Needs (70% = $980): rent $650, groceries $180, utilities $80, transport $70
- Savings/debt (20% = $280): $100 emergency fund, $180 extra debt payment
- Flex (10% = $140): personal spending, small household needs
Sample budget on $1,600/month take-home
- Needs (70% = $1,120): rent $750, groceries $200, utilities $90, transport $80
- Savings/debt (20% = $320): $120 emergency fund, $200 extra debt payment
- Flex (10% = $160): personal spending, small household needs
Sample budget on $1,800/month take-home
- Needs (70% = $1,120): rent $850, groceries $220, utilities $100, transport $90
- Savings/debt (20% = $360): $150 emergency fund, $210 extra debt payment
- Flex (10% = $180): personal spending, small household needs
Notice what changes between the examples: the structure stays identical, only the dollar amounts move. That is the whole point of a percentage framework — it scales with your income instead of breaking every time your paycheck changes.
Step 4: Cut Spending Without Making Life Miserable
When you are learning how to budget on a low income, forget the advice to cancel everything enjoyable. Sustainable cuts target the spending you will not miss. Start with the three areas where low-income households most often find painless savings:
Groceries. Food is usually the largest variable expense and the most controllable. Plan meals around affordable staples — rice, beans, lentils, oats, seasonal produce, eggs — and shop with a list. Store brands are typically identical in quality to name brands for basics. One fewer takeout meal a week often frees more money than any coupon strategy.
Subscriptions and fees. Audit every recurring charge: streaming services, apps, memberships, bank fees. Cancel what you do not use weekly. Call your phone and internet providers and ask for a lower rate or a hardship plan — retention departments exist precisely for this, and a ten-minute call can cut a bill for a full year.
Energy and transport. Small habits compound: LED bulbs, unplugging idle electronics, washing in cold water, and keeping tires properly inflated. If public transit is viable where you live, even replacing a few car trips a week trims fuel and wear costs noticeably.
Step 5: Handle Debt on a Small Budget
Debt feels like a trap when you are learning how to budget on a low income, because minimum payments barely touch the principal. Two things matter most: stop the bleeding, then pick a payoff order. First, avoid new high-interest debt wherever possible — payday loans and cash advances can turn a shortfall into a spiral. If you are already carrying balances, the avalanche method (paying minimums everywhere, throwing every extra dollar at the highest-interest balance) saves the most money mathematically; the snowball method (smallest balance first) wins on motivation. Either beats paying minimums alone.
Also know this: your credit score affects what you pay for insurance, deposits, and future borrowing, so protecting it is part of budgeting. If building or rebuilding credit is on your list, our guide on how to build credit from scratch walks through it without requiring existing credit. And if a collector is calling, you have rights — the CFPB’s library of answers to common money questions explains what debt collectors can and cannot do.
Step 6: Claim the Help You May Already Qualify For
This step is not charity and it is not gaming the system. Assistance programs exist precisely for households budgeting on low incomes, and claiming benefits you qualify for is as legitimate as claiming a tax deduction. Eligibility rules and benefit amounts vary by state, household size, and income, so treat the programs below as starting points and check your own eligibility:
- SNAP (food assistance): monthly funds for groceries for qualifying households. Apply through your state’s SNAP agency.
- LIHEAP (energy assistance): help with heating and cooling bills, and sometimes weatherization, for qualifying households.
- Food banks and pantries: no-application-needed groceries in most communities; many also help with diapers, pet food, and referrals.
- Earned Income Tax Credit: a federal tax credit for working people with low to moderate incomes that can mean a significant refund — check the official Earned Income Tax Credit page to see if you qualify and claim it.
The fastest way to see the full menu of programs in one place is USAgov’s benefit finder, which matches your situation to federal and state assistance you may be eligible for. A single application session can surface help with food, housing, healthcare, and utilities you did not know existed.
Step 7: Grow the Income Side of the Equation
When learning how to budget on a low income, there is a floor to how far cutting can take you, and no ceiling on earning more. If your needs consistently exceed 70% of take-home pay, the honest fix is more income, not more austerity. That does not have to mean a second full-time job — even a few extra hours a week of flexible work changes the math of a tight budget dramatically.
Start with what fits your schedule and skills: delivery and rideshare gigs, freelancing, selling unused items, or turning a skill into a small service. Our roundup of side hustles you can start with no money is built for exactly this situation — every idea in it starts at zero cost. Direct the extra income deliberately: half to the savings/debt bucket, half to breathing room, so the hustle improves your life now and your future simultaneously.
Protect the Plan: A Starter Emergency Fund
The 20% bucket has an order of operations. Before attacking debt aggressively, build a small emergency buffer — even $500 to $1,000 — in a separate savings account. Without it, every surprise (a car repair, a medical bill) lands on a credit card and undoes months of progress. Once the buffer exists, redirect that 20% toward high-interest debt, then toward longer-term goals.
And when the debt is under control and the buffer is funded, that same 20% becomes your wealth-building engine. It does not take much to begin: our guide on how to start investing with little money shows how small, consistent contributions compound over time. Budgeting on a low income is not the end goal — it is the launchpad.
Frequently Asked Questions
Can you really budget on a very low income?
Yes — budgeting matters more when money is tight, not less. The key is using a framework built for low incomes (like the adapted 70/20/10 split above) instead of classic rules designed for median salaries, and planning from your lowest typical month so the budget survives slow periods.
What is the 70/20/10 budget rule?
It is an adaptation of the classic 50/30/20 rule for tight incomes: roughly 70% of take-home pay for needs, 20% for savings and extra debt payments, and 10% as guilt-free flex spending. It acknowledges that housing costs consume a larger share on low incomes while keeping the savings habit alive.
How much should I save per month on a low income?
Any consistent amount counts. If 20% is out of reach, start with 5% or even a flat $25–$50 a month and increase it as income grows or debts shrink. Consistency beats size — a small automatic transfer you never miss builds both savings and the habit.
Should I pay off debt or save first?
Do both in sequence: build a small $500–$1,000 emergency buffer first so surprises do not land on credit cards, then direct the savings bucket toward high-interest debt using the avalanche or snowball method. Keep making minimum payments on everything throughout.
What assistance programs help low-income households?
Common ones include SNAP for groceries, LIHEAP for energy bills, local food banks and pantries, and the Earned Income Tax Credit at tax time. Eligibility varies by state, household size, and income — USAgov’s benefit finder is the quickest way to see what you may qualify for.
How do I budget with irregular income?
Base the entire budget on your lowest month from the last three, so essentials are always covered. In better months, follow a priority list for the surplus: top up the emergency fund, make an extra debt payment, then allow a little flex spending. Never upgrade fixed expenses (rent, car payment) based on a good month.
Conclusion
Learning how to budget on a low income is not about deprivation — it is about direction. Find your real number, track where it goes, run it through the 70/20/10 framework, trim the spending you will not miss, handle debt strategically, claim the assistance you qualify for, and grow income where you can. None of these steps requires earning more first; they work with the paycheck you have today. Start with one step this week — even just tracking your spending — and let the system compound from there. Future-you is counting on the plan you build right now.
[…] tight, getting your spending plan under control first makes everything else easier — our guide to budgeting on a tight income walks through a realistic framework for that. And once your credit is established and your budget […]
[…] out what you don’t use, donate it, and then organize what’s left. This pairs well with budgeting on a low income — the cheapest storage upgrade is owning less […]
[…] land client number one using products from home and restock from that first payment. If you are budgeting on a low income, treat this list as a priority order, not an all-or-nothing shopping […]
[…] remember the budget angle: whichever you choose, the machine is only part of budgeting for college expenses — accessories, software subscriptions, and a good backup drive add up too. Students watching […]
[…] baseline — and a target. If you’re serious about tightening the whole budget, our guide to budgeting on a low income walks through building a full spending plan around that […]
[…] fall, and watching numbers shrink is one of the most motivating parts of the whole process. If budgeting on a low income is already part of your routine, fold this debt list right into that budget so the payoff amounts […]
[…] shares when prices dip and fewer when they rise. If $625 feels steep, start with what fits your budget and increase it with every raise. Consistency beats amount in the early […]
[…] in cash — long-haul and last-minute — while paying cash for cheap short hops. If you’re building a travel budget on a low income, treat points as a separate savings account: earn on everyday spending you’d do anyway, […]